Last week, in Part 1 of the Access Test, we looked at where your extra money goes each month. This week is Part 2: when you need that money back, what does it take to get it?
Say you need $4,000 by Friday. A car repair, a slow week in your side business, a bill that shows up early. Where does it come from, and what does it take to get it?
Ask four questions about every place your extra money sits.
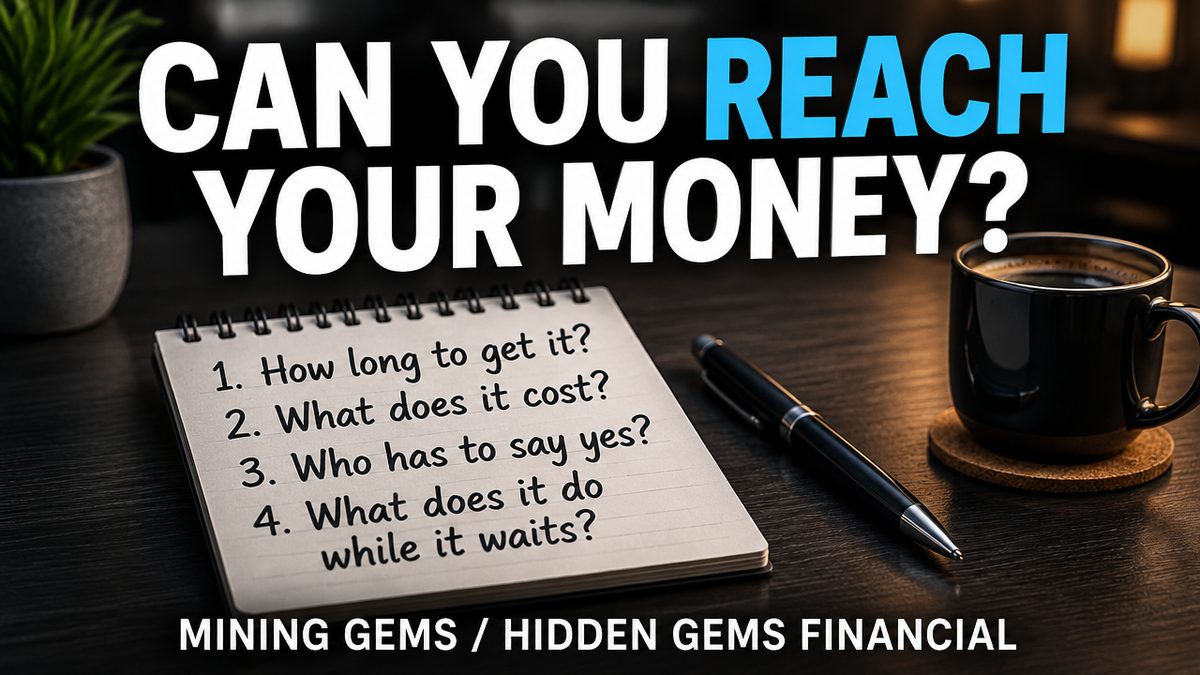
- How long will it take to get it? Minutes, days or weeks.
- What will it cost? Interest, fees, taxes or penalties.
- Who has to say yes? A lender, a plan administrator, or only you.
- What does the money do while it waits? Does it still work for you, or does it just sit?
Run the four questions on the places most families use
Savings account. Easy to reach, and you are the one who says yes. Growth is usually slow, and the interest you earn is generally taxable. Every dollar you pull out stops growing, and that lost growth stays lost until you replenish the account.
Extra on the mortgage. It lowers what you owe, but the money is now in your house. To use your own equity you generally have to apply for a home equity loan or line of credit and get approved. That takes time, and approval is not guaranteed.
A line of credit is like a card in a drawer. If you set it up while you do not need it, you are not starting an application on the day you need the money. Here is a simple example with round numbers. Say you have a $50,000 line and you use $4,000 of it. Interest applies to the $4,000 you used, not to the full $50,000. It is usually a variable rate, your home is the collateral, and terms vary, so talk to a lender first.
Credit card payments. Paying down a high rate balance is often a smart move. Once it is paid, that money is gone, and a new need can put you right back on the card.
Using a card when you need cash. It is fast, but the interest rate is high unless the card is managed carefully. That is a longer conversation for another day.
401(k) up to the match. The match is real value. But the money is exposed to market ups and downs, and it is generally meant to stay until retirement. A car repair or a slow week is usually not a qualifying event, so you may not be able to take it out at all. Taking it out early can mean taxes and penalties, and you could be pulling it out when the market is down. Ask your plan administrator what your plan allows.
None of these is wrong. The point is to see the whole picture and know which one you would reach for first.
Your money has two jobs
The first is what it does when you spend it. The second is what it can still do for you afterward. That is question four, and most families only ever give their money the first job.
One question answered
If I put extra money on my mortgage, can I get it back out if I need it? Not by simply taking it back. Extra payments lower what you owe, but to use that equity you generally have to apply for a home equity loan or line of credit and get approved, and approval is not guaranteed. Before you send extra to the mortgage, ask where else you could reach $3,000 to $5,000 without an application. A lender can explain rates and terms, and a tax professional can tell you how any of it fits your taxes.
Here is how I work. No countdown clocks, no promises about returns, no pressure. I look at your real numbers, show you the trade-offs in plain English, and you decide. If it makes sense to keep going, we do. If it doesn't, you still leave with a clearer picture than you came in with.
If you want help walking through your own numbers, pick a time that works for you. It is a short, no pressure conversation. Book your call and let's get acquainted.
This is general education, not tax, legal or investment advice. Examples are simplified and not a guarantee of results. Loans, withdrawals and early access can have costs, fees and tax effects. Investments in a 401(k) or other market accounts can lose value. Terms and rates vary by lender and plan. Talk with a licensed professional about your own situation.